Blog
Investment Scams in Nigeria 2026: How to Spot Them Before You Lose Your Money
Introduction: Nigeria's Investment Scam Crisis in 2026
In May 2026, thousands of Nigerians woke up to locked offices, disconnected phone lines, and missing organisers. The XM investment scheme had collapsed overnight, joining a long list of fraudulent operations that have stripped ordinary Nigerians of savings, school fees, and business capital. With Nigerian banks processing over N570 trillion in electronic transactions and the naira under continued FX pressure, fraudsters have never had a larger pool of desperate, opportunity-seeking targets.
This is not a breaking news piece. This is a practical guide — built around pattern recognition — so that the next time a scheme approaches you, you see it for exactly what it is before you hand over a single kobo.
5 Common Investment Scam Types Targeting Nigerians in 2026
1. Ponzi and Pyramid Schemes
These are the oldest tricks in the fraud playbook, yet they keep evolving. A Ponzi scheme pays early investors using money collected from newer ones — not from any real business activity. When recruitment slows or organisers decide to run, the whole structure collapses. In Nigeria's 2026 landscape, these schemes often dress themselves up as "cooperative investment clubs," "mutual fund networks," or branded apps with professionally designed dashboards. The collapse of XM Lagos is a textbook example: fixed daily returns, no verifiable underlying business, and an office that ceased to exist the moment withdrawals exceeded deposits.
2. Fake Forex and Crypto Trading Platforms
Fraudsters clone the interfaces of legitimate trading platforms and offer "managed trading accounts" where a so-called expert trades on your behalf. Victims see their balance growing on the app — until they try to withdraw. At that point, they are asked to pay a "tax clearance fee," a "withdrawal insurance," or a "verification deposit." None of these are real requirements on any regulated platform. The money is gone, and so are the operators.
3. WhatsApp Investment Groups
A contact — sometimes a person you trust — adds you to a group where members share daily "payout screenshots." The testimonials feel organic, the chat is active, and someone always seems to have just cashed out. These groups are entirely staged. Screenshots are fabricated, and the group admin is the only person who ever actually receives money. By the time you contribute, you have already been profiled: your level of trust, your available cash, and how long you can be strung along before demanding a withdrawal.
4. Fake Real Estate and Land Investment Schemes
Scammers present professional brochures for housing estates in developing areas of Lagos, Abuja, or Port Harcourt. They offer guaranteed rental income or rapid capital appreciation. Site visits are either staged or show undeveloped land with no legal documentation. Victims pay for plots that either do not exist, are government-acquired land, or are sold simultaneously to dozens of other buyers. With property records still largely fragmented in Nigeria, verification is difficult — which is exactly why this scam thrives.
5. Fake Investment Apps and Tech Support Fraud
Fraudulent investment applications appear on social media, promising 30–50% monthly returns. Some have functional interfaces, customer support chat, and referral programmes. Others begin as tech support fraud: someone contacts you claiming your bank account or crypto wallet has been compromised, then walks you through "securing" your funds — directly into their wallet. The growth of mobile money and instant transfers in Nigeria has made this category of fraud faster and harder to reverse.
7 Red Flags: Your Investment Scam Checklist
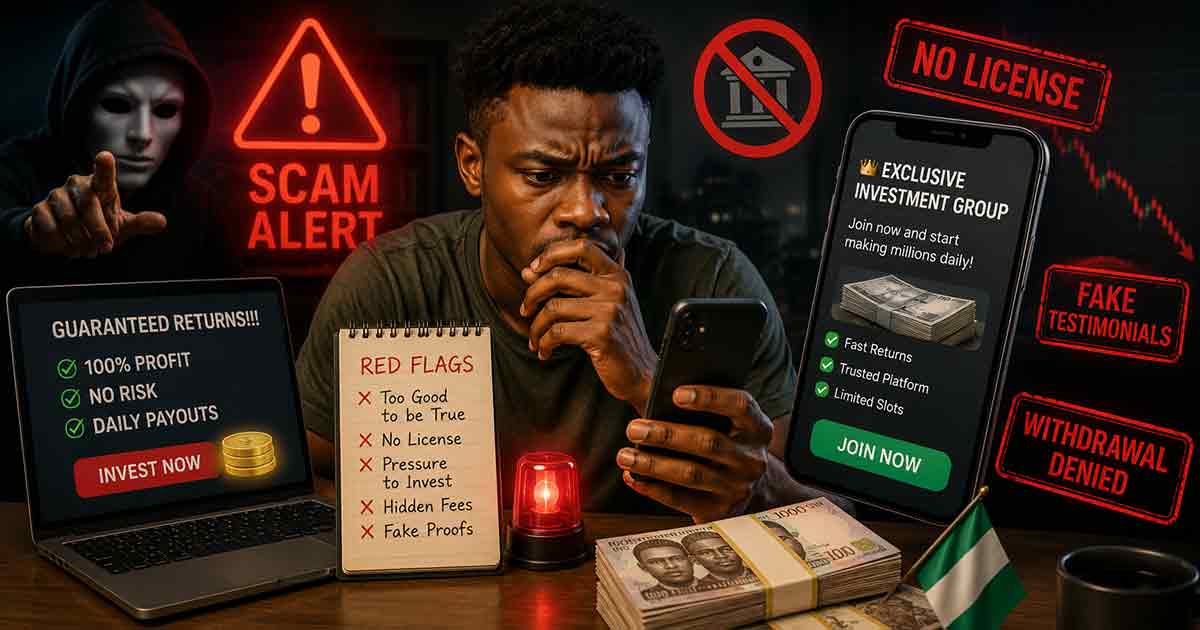
Before committing any money, run through this checklist. A single red flag is a warning. Multiple red flags mean you should walk away without engaging further.
- Guaranteed returns. No legitimate investment can guarantee fixed returns. Markets fluctuate. Any scheme promising "10% monthly, every month, no risk" is lying to you.
- Pressure to recruit. If your earnings depend primarily on how many people you bring in rather than the performance of an underlying investment, it is a pyramid structure, not an investment.
- No SEC or CBN registration. Legitimate investment firms operating in Nigeria must be registered with the Securities and Exchange Commission (SEC Nigeria). Ask for their SEC registration number and verify it at sec.gov.ng.
- Withdrawal conditions that keep changing. Legitimate platforms have clear, published withdrawal terms. If you are repeatedly asked to pay fees before accessing your own money, you are being scammed.
- Anonymous or unverifiable operators. You should be able to find the names, professional histories, and physical addresses of the people managing your money. If they exist only on Telegram or WhatsApp, that is a serious problem.
- Urgency and exclusivity. "This window closes tonight." "Only 20 slots left." These are sales tactics designed to prevent you from doing due diligence. Legitimate investments do not expire overnight.
- Returns that outperform every legitimate instrument. Nigerian Treasury Bills, regulated money market funds, and vetted equities offer real but modest returns. Any scheme offering dramatically higher consistent returns without a clear, verifiable business model is fabricating those numbers.
What to Do Immediately If You Have Been Scammed
Speed matters. The faster you act, the better the chance of limiting your losses or triggering a trace.
- Stop all further payments immediately. Do not pay any "release fee," "tax clearance," or "insurance deposit" — these are part of the scam, not solutions to it.
- Document everything. Screenshot conversations, save receipts, note transaction reference numbers, and record the names and phone numbers of everyone involved. Do not delete anything.
- Contact your bank directly. If a transfer was made recently, your bank may be able to flag the receiving account or initiate a recall. Time is critical — call your bank's fraud line immediately.
- Do not accept "recovery" offers. After a scam, victims are frequently targeted by recovery fraud: someone claims they can retrieve your money for an upfront fee. This is a second scam layered on the first.
Where to Report Investment Fraud in Nigeria
Reporting may not recover your money, but it creates a paper trail, alerts regulators, and potentially protects others. Use all relevant channels:
- SEC Nigeria (Securities and Exchange Commission): Report unregistered investment schemes at sec.gov.ng or call their investor protection line. SEC has the mandate to prosecute illegal fund managers.
- EFCC (Economic and Financial Crimes Commission): File a petition at efccnigeria.org or visit any EFCC zonal office. The EFCC handles financial fraud and has prosecuted Ponzi operators in the past.
- FCCPC (Federal Competition and Consumer Protection Commission): For consumer-facing fraud, especially fake apps and digital platforms, file at fccpc.gov.ng.
- Your bank's fraud desk: Every commercial bank in Nigeria is required to maintain a 24-hour fraud reporting line. Use it as your first call if the transaction was recent.
- Nigeria Police Force: File a formal report at your nearest station. This creates an official record and supports any future legal proceedings.
How to Invest Safely Instead
The solution to Nigeria's investment scam epidemic is not to stop investing — it is to invest in regulated, verifiable instruments. Here are safe alternatives:
- Nigerian Treasury Bills and FGN Bonds: Issued by the federal government and accessible through any commercial bank or the CBN. Your capital is as secure as the sovereign.
- SEC-registered mutual funds: Platforms like Stanbic IBTC, ARM Investment, and Cowrywise connect users to regulated fund managers. Returns are not guaranteed but are real and audited.
- Listed equities on the Nigerian Exchange (NGX): Buying shares through a registered stockbroker gives you ownership in real companies with published financials.
- Dollar-denominated savings products: Several licensed fintech firms now offer dollar savings accounts with transparent interest structures, protecting against naira depreciation without involving unregulated crypto schemes.
The common thread across all safe investments: you can independently verify the operator's registration, read their audited financials, and withdraw your money through clearly published processes.
Conclusion: Scepticism Is Not Paranoia — It Is Protection
In 2026, Nigeria's digital financial infrastructure is genuinely growing. Electronic transactions are at record volumes, and legitimate investment options are more accessible than ever. But the same infrastructure that enables real wealth-building also enables fraud at unprecedented scale and speed.
The XM scheme collapse in Lagos is not an isolated incident. It is a symptom of a pattern that repeats every few years with a new name, a new app, and a new set of victims. Pattern recognition — not just awareness — is what breaks that cycle. When an investment promises what no legitimate market can deliver, the correct response is not curiosity. It is to walk away, document what you saw, and report it so others are warned.
Your money took real work to earn. Protect it with the same rigour.