Blog
Why the Naira Keeps Falling Against the Dollar And What to Do About It
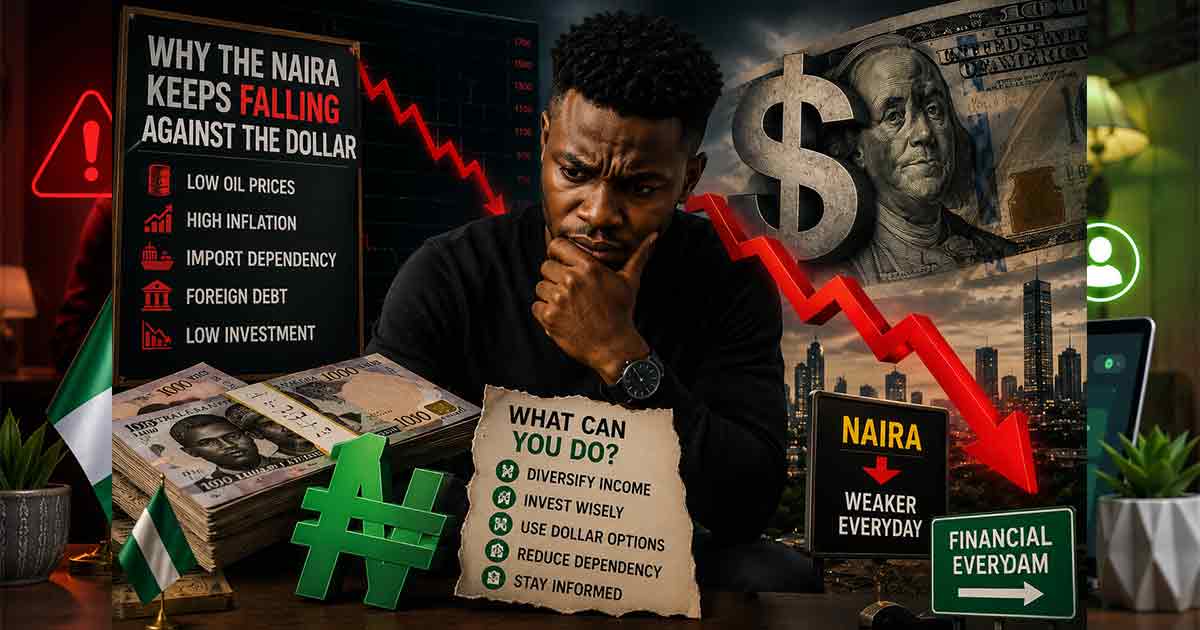
Introduction: The Naira's Long Slide
If you've tried to send money abroad, pay for a subscription service in dollars, or simply buy imported goods in Nigeria recently, you've felt it — the naira is worth less than it was last year, and significantly less than it was five years ago. The exchange rate that once hovered around ₦360 to the dollar now sits well above ₦1,500, and for millions of Nigerians, that gap represents real pain: shrinking salaries, rising prices, and savings that quietly lose value every month.
This isn't just bad luck or mismanagement at any single point in time. Naira depreciation is the product of deep, structural forces — some global, many homegrown. Understanding those forces is the first step toward protecting yourself from them.
5 Root Causes of Naira Depreciation
1. Nigeria's Heavy Dependence on Oil Revenue
Nigeria earns the vast majority of its foreign exchange through crude oil exports. When global oil prices fall or domestic production drops — whether due to pipeline vandalism, ageing infrastructure, or OPEC output cuts — the country earns fewer dollars. Fewer dollars flowing into the economy means the naira has less hard currency backing it. The country's FX inflows have been declining for years, and that structural weakness shows up directly in the exchange rate.
2. Falling Foreign Reserves
Nigeria's external reserves act as a buffer: the Central Bank of Nigeria (CBN) uses them to defend the naira by selling dollars when demand spikes. But when reserves fall — as they have in multiple periods over the past decade — the CBN's ability to intervene shrinks. Lower reserves signal vulnerability to currency speculators and make it harder to stabilise the rate even when the CBN wants to act. A country with thin reserves has little room to absorb shocks.
3. High Import Dependency and the Dollar Demand Problem
Nigeria imports a vast range of goods: fuel, food, machinery, electronics, pharmaceuticals, and more. Every one of those imports requires dollars. When demand for dollars consistently outstrips the supply coming in, the naira weakens. This imbalance — sometimes called a structural trade deficit — is worsened by the fact that Nigeria's non-oil export sector remains underdeveloped. There simply aren't enough dollars entering the economy through other channels to match what leaves through imports.
4. Inflation and Loss of Monetary Credibility
Inflation erodes a currency's purchasing power domestically, and if domestic inflation runs significantly higher than in trading partner countries, the exchange rate tends to adjust downward over time to reflect that divergence. Nigeria has consistently experienced double-digit inflation. When people don't trust that their naira savings will hold value, they rush to convert to dollars — adding even more pressure to the exchange rate and creating a self-reinforcing cycle.
5. Policy Uncertainty and Multiple Exchange Rate Regimes
For years, Nigeria operated multiple official and unofficial exchange rates simultaneously — the CBN rate, the I&E window, the parallel market — creating confusion, arbitrage opportunities, and distortions that drained reserves and discouraged foreign investment. While recent reforms have moved toward a unified rate, legacy distortions linger. Foreign investors remain cautious. Repatriation of profits is still complex. Until Nigeria's exchange rate policy is consistently transparent and predictable, capital will hesitate to flow in at the scale needed to stabilise the naira.
The Real Impact on Everyday Nigerians
The statistics are abstract, but the consequences are not. A naira that has lost 70–80% of its dollar value over a decade means:
- Imported goods are dramatically more expensive — from cooking gas to car parts to school textbooks printed abroad.
- Salaries paid in naira buy far less — even when nominal wages increase, they rarely keep pace with depreciation-driven price rises.
- Tuition, subscriptions, and travel priced in dollars become increasingly out of reach — paying for Netflix, school fees abroad, or a flight now costs multiples of what it did a few years ago.
- Savings held in naira quietly deflate — ₦1 million sitting in a savings account at low interest earns far less than the purchasing power lost to depreciation and inflation combined.
The impact is not evenly distributed. Those with access to dollar income, foreign assets, or digital currencies have fared considerably better than wage earners holding naira alone.
5 Practical Strategies to Protect Your Purchasing Power
1. Hold a Portion of Savings in USDT or Dollar-Denominated Assets
USDT (Tether) is a stablecoin pegged 1:1 to the US dollar and widely available on Nigerian crypto exchanges and peer-to-peer platforms. Holding some savings in USDT means your money moves with the dollar, not the naira. When the naira falls further, your USDT holdings are worth proportionally more in naira terms. This isn't a speculative bet — it's a hedge. Platforms like Binance P2P, Yellow Card, and others allow Nigerians to buy and hold USDT directly. Always use reputable platforms and understand the regulatory environment before moving funds.
2. Open a Domiciliary Account
Nigerian commercial banks offer domiciliary accounts that hold foreign currencies — typically USD, GBP, or EUR. If you earn in dollars (freelance payments, diaspora remittances, or export income), keeping that money in a domiciliary account rather than immediately converting to naira protects you from depreciation. Even partial conversion — spend naira for daily needs, keep the rest in the dom account — reduces your exposure significantly.
3. Invest in Dollar-Denominated Products
Several Nigerian fintech platforms now offer dollar savings and investment products — Eurobonds, US money market funds, or dollar-denominated mutual funds accessible from Nigeria. Products through platforms like Risevest, Bamboo, or Chaka allow Nigerians to invest in foreign assets with relatively low minimums. These instruments offer both currency protection and potential investment returns, addressing two problems simultaneously.
4. Consider Real Assets as an Inflation Hedge
Land and real estate in Nigeria, while illiquid, tend to hold value against inflation over long periods. Agricultural land, commercial property in growing cities, and even quality residential property in key markets have historically provided better inflation protection than naira savings accounts. Real assets won't protect you specifically against naira-dollar depreciation, but they insulate against the domestic purchasing power erosion that runs alongside it.
5. Develop or Monetise Skills That Earn in Foreign Currency
The most durable long-term hedge is income diversification. Remote work, freelancing on global platforms (Upwork, Fiverr, Toptal), content creation for international audiences, and digital product sales priced in dollars all generate income that naturally hedges your naira exposure. Nigerians are increasingly competitive in software development, design, writing, and virtual assistance. If you can earn even a portion of your income in dollars, the exchange rate works for you rather than against you.
What the CBN Is Doing — and What It Can't Fix Alone
The Central Bank of Nigeria has been active on multiple fronts: raising the Monetary Policy Rate (MPR) to attract capital and combat inflation, pushing for a more unified exchange rate to close the arbitrage gap between official and parallel markets, and working to clear a backlog of outstanding dollar obligations that had spooked foreign investors.
These are real, necessary steps. But monetary policy has limits when the underlying structural problems — oil dependency, thin reserves, import reliance, and weak non-oil exports — remain unresolved. The CBN can manage the symptoms; the cure requires broader economic transformation that takes years, not months.
The MPC's recent meetings have signalled a cautious tone: acknowledging inflationary pressure while watching for signs that the rate environment is tight enough to support the naira without strangling growth. It is a difficult balance, and no central bank can walk that line perfectly.
Conclusion: You Can't Control the Policy — But You Can Control Your Exposure
The naira's depreciation is not going to reverse overnight. The structural forces driving it are real, deeply rooted, and not fully within any government's immediate control. What you can control is how much of your financial life is exposed to naira-only risk.
A simple starting point: hold 20–30% of your liquid savings in a dollar-denominated form — whether USDT, a domiciliary account, or a dollar investment product. Explore at least one income stream with foreign currency potential. Understand the products available to you. Don't wait for a better rate that may not come before acting.
The Nigerians who navigate currency risk best aren't necessarily the wealthiest — they're the ones who took deliberate, early steps to diversify their financial exposure. That option is more accessible today than it has ever been.